CISMEA's Li Jinhu: From Online Best-Sellers to Securing Shelf Space in European and American Supermarkets, Chinese Brands Must Clear Four Hurdles
[Ebrun Original] Online retail in the United States is already highly mature, yet according to quarterly retail data released by the U.S. Census Bureau, e-commerce still accounted for less than 20% of total U.S. retail sales in the second quarter of 2026. For many Chinese brands that have grown up relying on platforms like Amazon, offline remains a vast market and a business system that must be relearned.
Does a product that sells well online naturally achieve greater sales volume after entering mainstream supermarkets such as Walmart and Costco? The answer is not as straightforward as it appears.
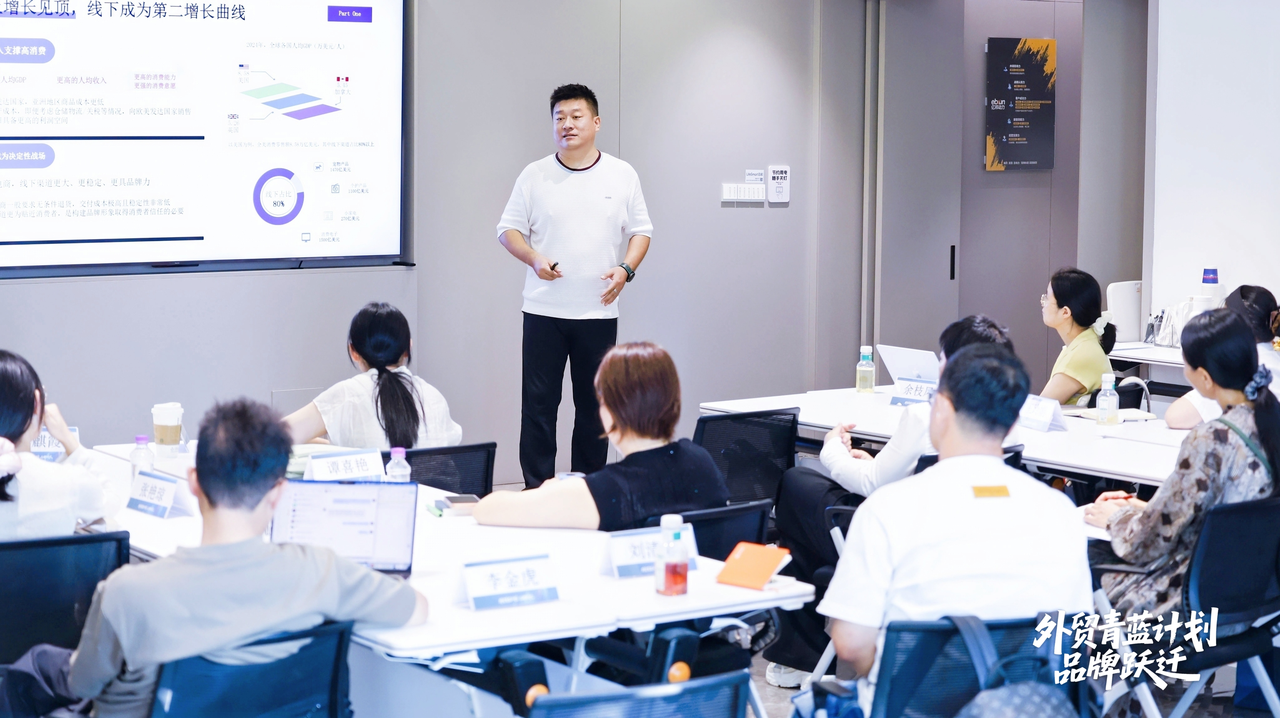
On October 20, at the third session of the 'Foreign Trade Blue-green Plan · Brand Leap' program—guided by the China (Hangzhou) Cross-Border E-Commerce Comprehensive Pilot Zone and the Xiaoshan District Commerce Bureau of Hangzhou—and hosted by the Global Cross-Border E-Commerce Knowledge Service Center and Ebrun's Matishe, CISMEA co-founder Li Jinhu first posed a question to the companies in attendance: 'If a supermarket placed an order with you tomorrow, would you be ready?'
The preparation he referred to involves pricing, products, cash flow, warehousing, returns, marketing, and organizational coordination. If any one of these is not designed in advance, an apparently attractive supermarket order can turn into operational pressure.
Li Jinhu has long focused on Chinese brands entering offline retail channels in Europe and the United States. In his account, moving from online to offline represents a gear shift in business logic: online data can validate demand, while offline channels require brands to re-prove that products can continuously turn over within limited shelf space and that the company can reliably fulfill orders over a longer operating cycle.
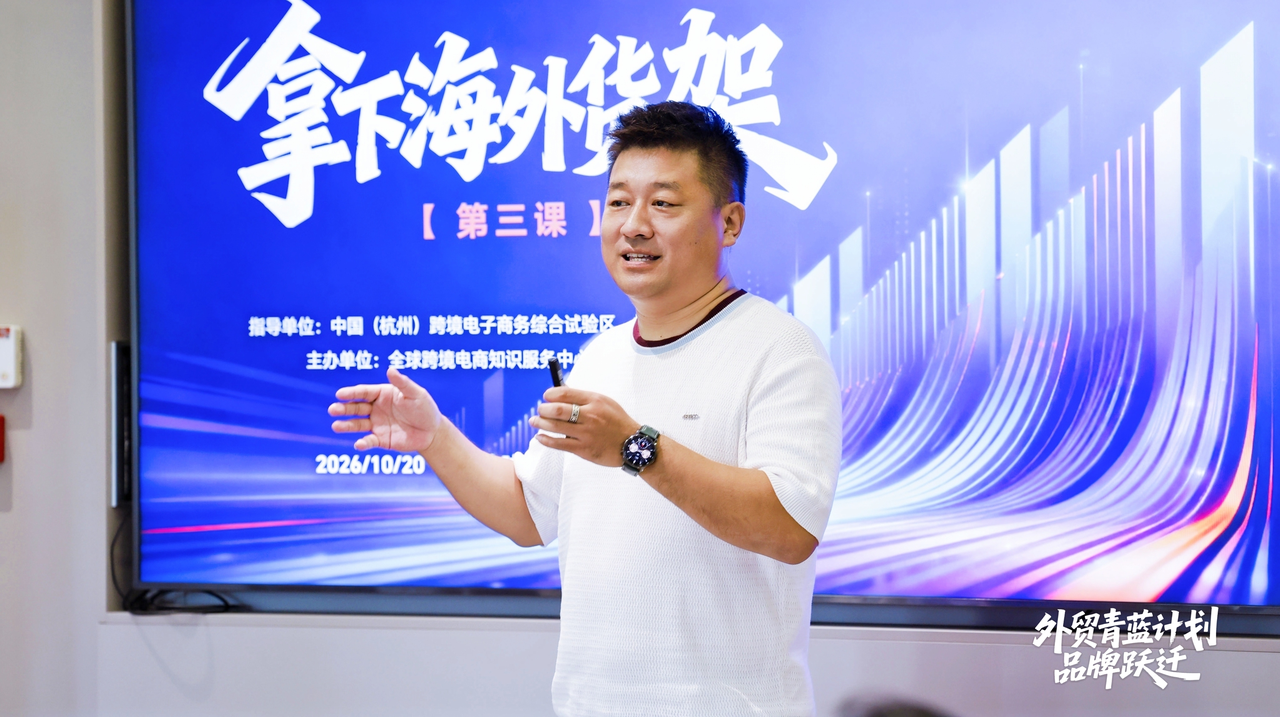
CISMEA Co-founder Li Jinhu
Why Do Buyers Still Shake Their Heads When Amazon Sales Are Strong?
For cross-border sellers, online platforms offer a relatively clear operating path: list products, acquire traffic, observe conversion, and then adjust advertising and inventory based on data. When a product reaches the top of its category, companies easily interpret that achievement as a passport to offline retail.
But physical supermarket shelves are limited, and every position has a clear opportunity cost. When a buyer brings in a new product, it means another product may have to exit; if the new product turns over slowly, the individual purchase, store sales per square foot, inventory, and the buyer's own decision record will all be affected.
Therefore, online sales are only one dimension by which buyers evaluate a brand. According to the judgment Li Jinhu presented in the course, online performance can help a brand get a ticket to talk to buyers, but it cannot directly earn supermarket admission. Buyers will also ask: How much gross margin can the product leave for the channel? How fast is turnover? How high is the return risk? Can the supplier deliver reliably? How many resources will the brand invest to drive sell-through?
Pricing structure is the first conflict companies encounter. Online platforms and offline channels have different cost structures; supermarkets need to reserve room for shelf space, staff, warehousing, promotions, and returns processing. If a product has long relied on low prices to achieve online sales, the profit left for offline channels may already be insufficient. Membership-based supermarkets may also require exclusive pricing or additional bundles, which can in turn create price collisions with online channels.
Companies can develop exclusive models for offline, but an unproven new product cannot directly inherit all the credibility of an online hit. Existing brand awareness can reduce the buyer's cost of understanding, but whether a new product can sell in stores still must be reassessed based on price, use case, and channel fit.
Online results prove that consumers once chose you; offline channels care about whether that choice can continue to occur within a different transaction structure.
In a Purchase Order, What Exactly Is the Buyer Calculating?
Many companies, when first encountering overseas supermarkets, understand it as a large B2B order: the supermarket purchases, the brand delivers, and the transaction is complete. Li Jinhu cautions that although the purchase contract is signed with the channel, the goods ultimately still must be bought by consumers. Whether inventory can turn over, whether promotions are effective, and how returns are handled will all ultimately come back to the brand.
In this sense, cooperation between a brand and a supermarket is still a B2C business. The channel provides shelves and consumer touchpoints, while the brand must take responsibility for demand generation, product expression, and after-sales support.
Li Jinhu summarized the key conditions for a product to gain buyer acceptance into six aspects: localization, functionality, differentiation, packaging, price, and supply chain. Though these six appear scattered, they ultimately point to the same question—whether the company can translate product advantages into commercial language that buyers can judge and consumers can understand.
Technical teams are accustomed to talking about chips, specifications, and performance, while buyers care more about whether these technologies will bring new foot traffic, faster turnover, or lower returns. Li Jinhu gave examples: an accessory highly matched to a computer's color and form, or a set of cleaning tools that intuitively demonstrates a 'hands-free washing' experience, is often easier to understand than complex engineering terminology. Differentiation can come from function, or from a sufficiently clear use case.
Localization also occurs at the scenario level. The same product may be treated as a commuting tool in China but viewed as an extension of outdoor athletic capability in the United States. When the reason users buy the product changes, the target audience, selling points, and communication methods must change accordingly.
Packaging directly bears the communication task on the shelf. Online packaging prioritizes transport efficiency, while offline packaging must also let consumers see the product from a distance, quickly understand its purpose, and make a judgment without being able to open the box and experience it. Different supermarkets also have their own rules for display, bundles, and pallets, so packaging becomes part of both product strategy and channel strategy.
Buyers evaluate both the product and the operating plan: whether the channel can absorb it and whether consumers are willing to buy it.
Foreign Trade Blue-green Plan · Brand Leap
Why Charging Straight at Top-Tier Supermarkets May Be the Most Dangerous Shortcut
When companies decide to enter offline retail, the most common impulse is to go straight to national chains such as Walmart and Costco. Top-tier supermarkets cover many stores and offer strong brand endorsement, and they appear to be the fastest choice for scaling sales.
But the larger the channel, the higher the cost of trial and error. If a product sells poorly in national supermarkets, the channel record left behind may affect subsequent cooperation; as order scale expands, payment terms, inventory, returns, and promotional expenses will also expand accordingly. When a company has not yet validated its product and team's offline capabilities, a large order may instead expose the weaknesses of the entire system prematurely.
Li Jinhu roughly divides U.S. offline channels into comprehensive supermarkets, membership-based supermarkets, national vertical channels, and regional channels. Different channels have different selection priorities: comprehensive supermarkets focus on turnover and mass demand, membership stores emphasize member value and bundle differentiation, vertical channels place greater weight on matching products with professional scenarios, and regional channels can serve as an entry point for testing products and operational capabilities.
Cooperation models must also be adjusted according to the company's stage. Brands can build local teams to supply directly, use distributors to cover more stores, or have supermarkets purchase directly; OEM private-label work mainly accumulates manufacturing and fulfillment capabilities, with relatively limited accumulation of owned brand assets. Each model corresponds to different financial pressure, profit structure, team requirements, and inventory risk.
Therefore, before choosing a channel, companies must first answer four questions: Why must we do overseas offline retail? Do we currently have the real conditions to enter offline retail? Should we start with regional pilots or go directly into national channels? Can funding, organization, and time withstand the validation cycle of an offline business?
These four questions ultimately come down to three judgments: whether the goal is clear, whether the product and market have produced enough evidence to prove strength, and whether the company is prepared to bear the corresponding risks. Tight cash flow, products still undergoing frequent iteration, teams lacking offline operational knowledge, or merely chasing the brand halo of top-tier supermarkets all suggest that companies should first fill the relevant gaps before deciding the pace of entry.
'There is no absolute good or bad channel; it only depends on whether it matches the company's current stage of development.'
This also means that offline layout is better validated within a controllable scope: first confirm that product, price, and team can work in coordination, then gradually expand stores and regions. Entering more channels is only the result; the premise is that the company already knows where it fits and why it can sell well there.
After Being Selected by a Buyer, How Does a Brand Stay on the Shelf?
After a product is selected by a buyer, sell-through, after-sales, and brand operations still must be actively undertaken by the company. Li Jinhu summarized the relationship in one sentence: 'Successfully connecting with a buyer and getting a product into a channel is merely buying a ticket.'
After the ticket comes an operating chain longer than that of online.
Large supermarkets usually replenish through distribution centers in different regions, and orders are split into many small batches. Brands need to decide whether inventory should be placed in domestic warehouses, in transit at sea, in U.S. overseas warehouses, or in supermarket warehouses, ensuring both replenishment speed and control over warehousing and capital occupation. As cooperation channels increase, companies also need systems such as EDI to process orders, invoices, and logistics milestones.
Return plans also need to be designed in advance. Low-ticket products may be handled through markdowns, while high-ticket products require recovery, inspection, and refurbishment. Determining whether a product suits a certain channel requires examining sales performance, return reasons, and handling costs across the full life cycle at the same time.
Sell-through also requires active brand participation. Offline promotions involve store price tags, display resources, staffing arrangements, and channel communication, and decision cycles are often longer than online advertising. Brands need to plan promotional rhythms in advance and continuously explain product value to stores and consumers, rather than waiting for shelves to generate sales naturally.
The more difficult change occurs inside the company. Online teams are accustomed to evaluating work by immediate sales and advertising returns, while offline business has longer cycles for product selection, entry, and promotion. If the two teams share the same pricing, inventory, and assessment methods, conflicts are likely. The boss needs to define channel boundaries from the perspective of the overall brand and allocate corresponding products, budgets, and evaluation cycles.
Supply chain fulfillment, an omnichannel pricing system, localization capabilities, and online-offline organizational coordination constitute the four core offline channel capabilities summarized by Li Jinhu. Combined with the self-check list in the course slides, companies can also check item by item before formally entering a channel: whether product value is clear, whether price and packaging can fit the shelf, whether the supply chain can sustain replenishment, whether market evidence and the business proposal are sufficient, and whether local warehousing, after-sales, buyer maintenance, and internal responsibilities have been implemented.
This also explains the value of CISMEA sharing this methodology: translating the easily overlooked rules beyond buyer relationships into capabilities that companies can judge, prepare, and build item by item before entering a channel.
Moving from online validation to offline operations, Chinese brands gain broader consumer touchpoints but also must bear fuller brand responsibility. From selling well online to selling well offline, the test is whether a company can restructure the advantages of a product into an operating system that channels can absorb and consumers are willing to choose. (Ebrun Original / October 22, 2026)
The 2026 government work report of Xiaoshan District, Hangzhou, noted that Xiaoshan's cross-border e-commerce export scale has ranked first in the province. To deeply empower foreign trade enterprises in the district to achieve high-quality development and help traditional foreign trade upgrade and transform from 'product going global' to 'brand going global,' the Xiaoshan District Commerce Bureau of Hangzhou, with support from the China (Hangzhou) Cross-Border E-Commerce Comprehensive Pilot Zone, based itself on the local foreign trade and manufacturing foundation, relied on platforms such as the Global Cross-Border E-Commerce Knowledge Service Center, and launched the 'Foreign Trade Blue-green Plan · Brand Leap' series of cultivation activities for high-quality foreign trade enterprises in the district with hundreds of millions in scale.
'Foreign Trade Blue-green Plan · Brand Leap' is hosted by the Global Cross-Border E-Commerce Knowledge Service Center and Ebrun's Matishe. The series responds to the real difficulties foreign trade enterprises encounter when moving from 'product going global' to 'brand going global,' focusing on solving problems such as some enterprises prioritizing supply chains over brand building, price competition, and insufficient market pricing capability. It helps enterprises fill shortcomings in brand strategy awareness, make good use of digitalization, AI, and other tools, strengthen their competitiveness in going global, and cultivate more local Xiaoshan global brands.
This article was first published on the official website of Ebrun.
[Copyright Notice] Ebrun advocates respecting and protecting intellectual property rights. Without permission, no one is allowed to copy, reproduce, or use the content of this website in any other way. If any copyright issues are found in the articles on this website, please provide copyright questions, identification, proof of copyright, contact information, etc. and send an email to run@ebrun.com. We will communicate and handle it in a timely manner.
Translated by AI. Feedback: run@ebrun.com