Low-Value Parcel Volumes Halve! How Will Cross-Border Direct Shipping Logistics Survive After the EU's New Tariff Rules?
By Wang Yu | Edited by He Yang
[Ebrun Original] "The era of direct shipping logistics dominating the European region is over, but direct shipping providers are far from reaching a dead end in Europe," said Howard, an executive at a leading overseas warehouse service provider, in an interview with Ebrun. Since July 1, the EU has removed the customs duty exemption for imported small parcels valued at no more than ?150, imposing a flat ?3 duty based on the product's tariff classification. Starting in November, an additional proposed "small parcel handling fee" of around ?2 will also take effect. This means the direct shipping small parcel model, which once accounted for a significant share of cross-border e-commerce in Europe, is facing even tougher challenges. Claims like "the direct shipping model is dead" and "overseas warehouses will completely replace it" are widespread in the industry. Many cross-border sellers are anxious, accelerating business transformations or simply exiting the European market. Logistics providers at the center of the storm, however, offer feedback far more complex than outsiders might expect. After discussions with several leading logistics providers—some focused on direct shipping, others specializing in overseas warehousing and local fulfillment—Ebrun found both consensus and divergence in their assessments of the "post-tariff era." With the duty-free dividend gone, how has the cross-border e-commerce market in Europe experienced shock and restructuring? Does small parcel direct shipping have a future? How are sellers and logistics providers responding to these changes?
The Two Models Shift, Small Logistics Providers Exit Faster
In the first month after the EU's small parcel tariff policy took effect, cross-border logistics did not experience the predicted violent upheaval. Howard noted that the impact of the new policy is real, but compared to last year's concentrated customs clearance pressures in the U.S., which once paralyzed airports and customs, this shock has been relatively mild. One reason is that Europe's cross-border e-commerce compliance environment has always been stricter than the U.S., and sellers are already accustomed to it. Additionally, U.S. customs pressures were concentrated at major ports like Los Angeles and New York, whereas European ports and logistics routes are more dispersed, with air, sea, truck, and rail transport able to share the burden.
Industry insiders point out that Europe consists of multiple sovereign states; although the policy framework is trending toward unification, differences remain in industrial bases, customs clearance resources, and the concentration of fulfillment systems. Therefore, the implementation of the new policy is characterized by a fragmented, gradual transmission effect, making a "full-scale alert" unlikely. Although cargo flows remain smooth, specific fulfillment route changes are emerging: a shift is underway between local warehouse shipping and cross-border direct small parcel delivery. iMile observed that goods entering the European market are no longer primarily shipped as individual small parcels directly from China. Instead, they are increasingly imported in bulk via trunk lines, full containers, or LCL shipments, then broken down at European local warehouses for last-mile delivery. Consequently, the parcel mix handled by logistics companies is becoming more diverse. iMile found that some product categories that previously rarely used local warehouse shipping are now appearing in the parcels it handles. Pandi International has also noticed similar changes. Its overseas warehouse inbound categories are adjusting: lightweight small items that previously relied heavily on direct mail, such as 3C accessories, small home decorations, and small textile items, are now entering overseas warehouses in bulk. Its customer structure is also shifting: many sellers who previously focused on direct mail product listing are now proactively inquiring about overseas warehouse solutions; some existing customers are extending their stocking cycles, moving from "small quantities, frequent replenishment" to increasing safety stock and deepening inventory levels. In short, the new policy has directly stimulated the expansion of local logistics warehousing in Europe. CBRE data released in July shows that in its European survey, 75% of postal operators, 68% of third-party logistics providers, 54% of e-commerce companies, and 35% of omnichannel retailers plan to expand logistics warehouse space this year. CBRE also highlighted that Chinese companies, especially e-commerce firms, are particularly active; previously, they often obtained warehouse capacity indirectly through third-party logistics providers, but now more are directly leasing warehouse space.
In contrast, cross-border small parcel direct shipping logistics products have seen a significant decline. Air Cargo News data shows that by August, e-commerce air cargo export volumes from China to Europe had dropped 40% year-on-year. Customs data also illustrates this: at Belgian customs, a major clearance route for direct parcels into Europe, the number of small parcels entering via low-value simplified declarations (H7 channel) in July decreased by 53% year-on-year; meanwhile, cargo entering via full standard import declarations (H1 channel) surged by 102%. With this model shift, the average product value rose from ?5.73 to ?10.85, nearly doubling. Similar "one down, one up" trends are widespread in the Netherlands, Poland, Lithuania, and other European countries. Shifting from macro data to real business sentiment, a large logistics provider focused on direct shipping admitted that its European routes are indeed affected, with short-term order volumes dropping about 20%. Smaller freight forwarders face even tougher conditions. Multiple industry insiders told Ebrun that some forwarders have seen their European business volumes halve, relying on remaining North American orders to survive, with some account managers even leaving their jobs. However, the changes in the European small parcel direct shipping market cannot simply be interpreted as a market contraction. More precisely, this is a "structural consolidation" centered on service capabilities and industry barriers. Many logistics insiders point out that market volumes have adjusted, but providers with true fulfillment capabilities and compliance strength are becoming sellers' first choice. At the same time, many small providers are exiting because industry barriers are rising. Cross-border logistics is increasingly becoming a capital-intensive, compliance-heavy, and operationally complex industry. The space that once relied on low prices and gray clearance is being squeezed by both policy and market forces. This "top-tier siphoning" effect has made the decline among leading direct shipping providers more manageable, their recovery faster, and they can even offset overall market downturns and achieve counter-trend growth. For example, Yuntu Logistics' European routes are showing growth. It is reported that over the past few years, the company has continuously invested in aircraft capacity, transfer teams, and last-mile resources; these investments are now beginning to yield tangible results and translate into business gains after the new policy took effect.
The 'Basic Plate' of Cross-Border Small Parcel Direct Shipping Remains, but the Game Has Changed
How long will the downturn in the European small parcel direct shipping model last? Different logistics providers hold divergent views. One large logistics provider specializing in direct shipping told Ebrun that they expect the market to gradually recover in the fourth quarter, essentially reclaiming lost ground within the year. Other providers believe the market needs 12 to 18 months to fully absorb the policy changes. A consensus exists: the direct shipping model will not disappear due to new tariffs. Its most direct advantages are, first, capital efficiency—sellers do not need to pre-stock goods in European warehouses, reducing inventory capital occupation; second, category flexibility—new product testing, long-tail trial sales, and seasonal bestsellers can be launched quickly via direct shipping. Therefore, while it may no longer be the mainstream fulfillment method for most products, it will remain an important supplementary solution in certain scenarios, potentially even the most cost-effective one. Moreover, the "basic customer base" for direct shipping still has considerable scale in the short term. iMile points out that recently, some sellers who previously used the "direct shipping from China to Europe" model have begun inquiring about overseas warehouse and fulfillment services. However, transitioning from direct shipping to overseas warehousing requires rethinking inventory investment, SKU management, inventory turnover, and return handling, making it difficult for sellers to complete all adjustments in a short time. What is more likely is a phased migration: first, putting core SKUs in European warehouses; second, gradually expanding inventory based on actual sales velocity; third, further establishing a regional warehousing and distribution network.
Howard has observed similar trends. His assessment is that for traditional bulk sellers with hundreds of thousands or even millions of direct shipping SKUs, direct shipping is a path dependency that cannot be immediately severed. "Making a drastic break is extremely risky; it's impossible to immediately bet all share on warehouse shipping. Even converting just 20% of direct shipping SKUs to overseas stocking would require a staggering amount of capital, easily breaking a fragile cash flow. The 'low margin, high volume, wide net' product selection algorithm would also fail," he noted. At the same time, current air freight and labor costs are also declining, meaning the impact of tariffs, while significant, is not without offsetting room. As a transport mode heavily relied upon by cross-border e-commerce, China-Europe air cargo data fluctuation is one of the most intuitive indicators of the current direct shipping market situation. According to the latest WorldACD survey, after the new policy took effect in July, cargo volumes on relevant routes were significantly impacted, with August still showing contraction. However, entering September, weekly data has begun to show signs of "bottoming out": in August this year, Hong Kong-to-Europe air cargo volumes fell 30% year-on-year, down 24% from June before the new rules; but from weekly data, in the last week of August, Hong Kong-to-Europe route volumes rebounded 3% month-on-month, up 6% from the low two weeks earlier; China-mainland-to-Europe route volumes also left the downward track, with four consecutive weeks of modest month-on-month increases, slowly recovering. Switching from the industry-wide perspective to individual sellers, it's evident that many are sticking with the direct shipping model, though their tactics have changed. Ebrun observed that in the past, sellers commonly used marketing strategies encouraging consumers to "buy A along with B" (cross-category combination purchases), but under the new policy environment, they are now more likely to encourage repeat purchases of the same single item, such as three products with different specifications under the same HS Code, so that the three items incur only ?3 in duty, with each item bearing just ?1. If cross-selling, they use discounts like "second item X% off, third item X% off" to maintain reasonable profit margins while still offering incentives. This implies a shift in marketing logic: from "expanding categories" to "promoting repurchase," using multi-item discounts to guide consumers to increase per-order purchase quantities, thereby effectively diluting per-unit costs while maintaining direct shipping flexibility. Considering all factors, one large logistics provider specializing in direct shipping estimates that a reasonable future landscape would be: about 70% of volumes handled by overseas warehouses and the remaining 30% continuing via direct shipping. However, within that remaining "30%" of direct shipping volumes, traditional postal parcels might ultimately retain only a 3%-5% share, with the bulk of the remainder taken over by commercial express and line-haul parcels. The reason is that the latter offer better compliance, customs clearance efficiency, timeliness, and higher profit margins than postal parcels.
Low Prices Matter Less; Compliance Capability and Full-Chain Costs Become New Competitive Points
After the shakeout, sellers remaining in the European market are changing their criteria for selecting service providers: pure low freight rates no longer hold automatic approval. "Previously, many sellers chose providers based on a relatively simple standard, focusing first on per-parcel price. But in the current environment, comparing only prices without evaluating overall fulfillment capability could prove to be a short-sighted choice," said one industry insider. Customs clearance stability, timeliness certainty, exception handling capability, and compliance assurance—these are the keys to determining whether a supply chain can operate sustainably. After the new policy, gray clearance practices were eliminated, and compliance stability has become the hard currency in the cross-border logistics industry. Platform actions have already signaled this shift. Previously, some leading cross-border platforms publicly stated they would not cooperate with certain logistics companies, indicating that platforms have begun actively screening compliant and stable logistics providers. Pandi International also pointed out that the comprehensive tightening of EU customs compliance is not a "short-term push" but the "new normal."
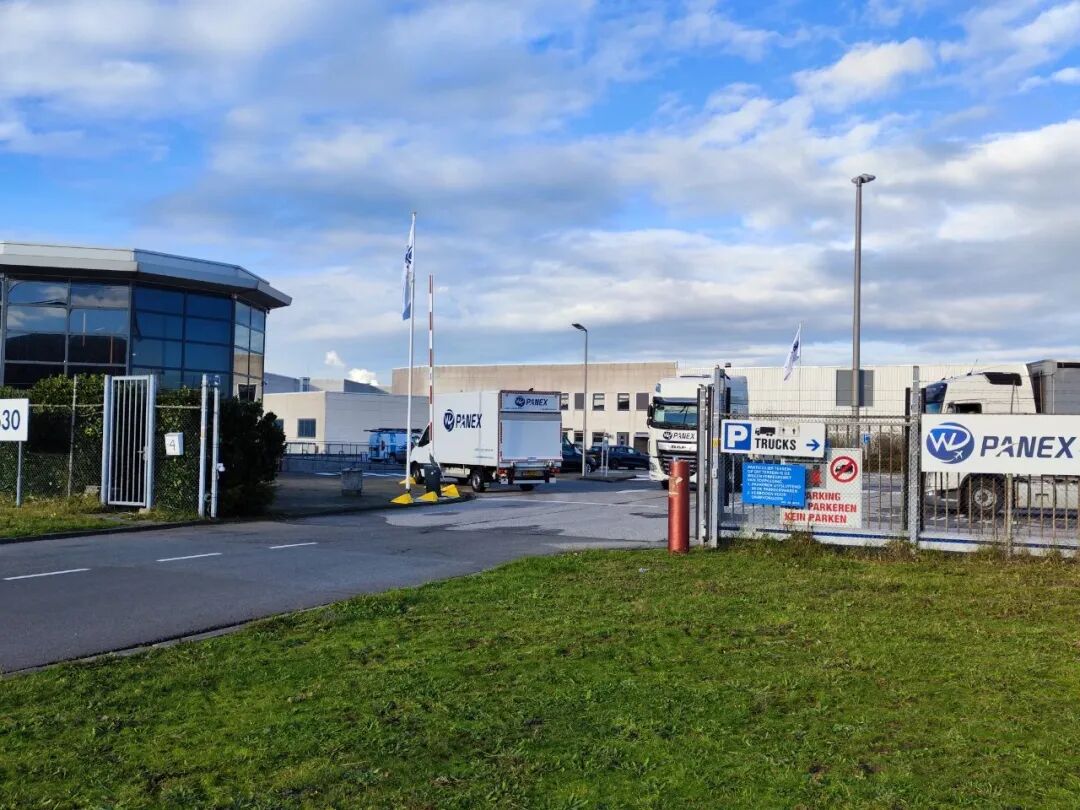
Beyond the significantly narrowed tolerance for tariff classification errors, the upcoming launch of a customs data center is even more critical. With cross-verification of e-commerce orders, logistics information, and declaration documents, methods like under-reporting, concealment, or illegal clearance will become impossible to hide. "Compliance is a two-way selection mechanism," Howard said. "If you are a compliant seller, you must also choose a compliant service provider because it will also screen for compliant customers to avoid having one non-compliant shipment causing an entire container to be detained." However, saying "low freight rates are not the primary issue" does not mean sellers are paying less attention to costs. In fact, as the proportion of warehouse shipping increases, this issue becomes more complex. Sellers' cost perspectives have extended from a single first-leg freight rate to a broader full-chain view, with many variables influencing decisions. For example, the importance of warehouse location (such as proximity to consumers) is rising. "In the past, people focused more on warehouse rent; now they consider a comprehensive account: warehouse storage costs, trunk line costs, in-warehouse operation costs, last-mile costs, delivery speed, and return costs," iMile told Ebrun. On the other hand, whether the overseas warehouse network is robust has become a focal point of industry competition. This year, various overseas warehouse providers have accelerated their expansions, such as: Pandi International is strengthening its core hub warehouses in the Netherlands and Germany while improving its regional sub-warehouse networks in Eastern and Southern Europe; Gu Cang's European warehouse cluster area exceeds 1.2 million square meters, a 71% surge year-on-year, spreading from the traditional "iron triangle" of the UK, France, and Germany to central, southern, and eastern Europe, spanning 15 countries; iMile, after completing its German last-mile network, has launched interline routes between Germany and Italy, with plans to gradually incorporate Spain, Hungary, and Poland into its last-mile network, aiming to build a "Pan-European logistics backbone network."
Ebrun continues to track and report on this intelligence. For more information related to this article, please scan the QR code to follow the author's WeChat.
This article was first published on the official website of Ebrun.
[Copyright Notice] Ebrun advocates respecting and protecting intellectual property rights. Without permission, no one is allowed to copy, reproduce, or use the content of this website in any other way. If any copyright issues are found in the articles on this website, please provide copyright questions, identification, proof of copyright, contact information, etc. and send an email to run@ebrun.com. We will communicate and handle it in a timely manner.
Translated by AI. Feedback: run@ebrun.com